


India's Sustainable Aviation Fuel Market Faces Feedstock Supply Challenges
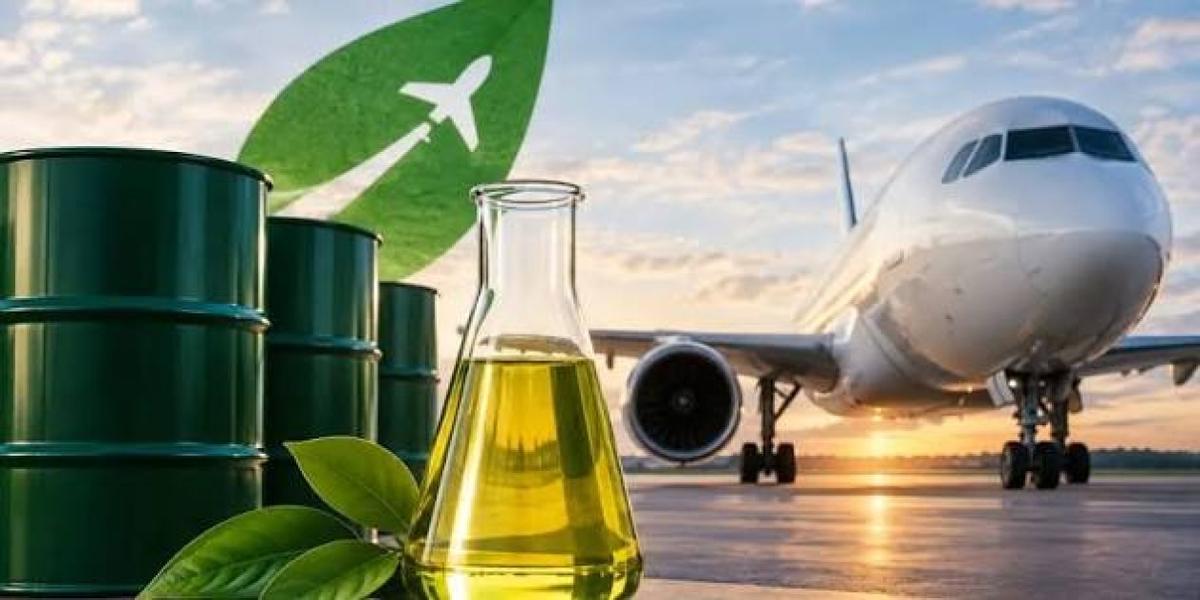
India's emerging sustainable aviation fuel (SAF) industry faces a critical supply-chain challenge as projected demand approaches 3.8 lakh tonnes annually by 2030, placing renewed attention on the availability and collection of used cooking oil.
Sustainable aviation fuel is being explored as an important tool for reducing greenhouse gas emissions associated with commercial aviation.
However, developing production capacity alone will not guarantee that India can meet its future SAF requirements.
Manufacturers also need reliable supplies of eligible raw materials, known as feedstocks, that can be processed into aviation fuel.
Used cooking oil is one such feedstock.
It can be converted into sustainable aviation fuel through established refining technologies, including the hydroprocessed esters and fatty acids pathway, commonly known as HEFA.
The principal challenge is that India's used-cooking-oil supply is dispersed across restaurants, hotels, commercial kitchens, food processors and smaller establishments.
Collecting it requires an organised network of suppliers, aggregators, transporters and processing facilities.
Without adequate collection systems, producers may struggle to secure sufficient feedstock at commercially viable prices.
The challenge is particularly significant as India develops plans for sustainable aviation fuel blending and seeks to support the decarbonisation of its expanding aviation industry.
The projected 3.8 lakh tonnes of SAF demand by 2030 highlights the scale of the opportunity, but also raises questions about feedstock availability, traceability, production costs and long-term supply security.
India Sustainable Aviation Fuel Market: Key Facts

|
Indicator |
Details |
|---|---|
|
Industry |
Sustainable aviation fuel |
|
Country |
India |
|
Projected SAF demand by 2030 |
Approximately 3.8 lakh tonnes annually |
|
Key feedstock under consideration |
Used cooking oil |
|
Major production pathway |
Hydroprocessed esters and fatty acids (HEFA) |
|
Main supply challenge |
Collection and aggregation of dispersed used cooking oil |
|
Potential feedstock sources |
Restaurants, hotels, food processors and commercial kitchens |
|
Relevant collection initiative |
Repurpose Used Cooking Oil (RUCO) |
|
Primary industry application |
Commercial aviation |
|
Main policy objective |
Lower lifecycle aviation emissions |
|
Other potential feedstocks |
Agricultural residues, municipal waste and other eligible materials |
|
Principal commercial constraints |
Feedstock costs, collection infrastructure, processing capacity and certification |
The 2030 figure is a demand projection rather than a confirmed production volume or guaranteed market outcome.
SAF Demand Could Reach 3.8 Lakh Tonnes by 2030
India's projected sustainable aviation fuel requirement of approximately 3.8 lakh tonnes by 2030 reflects the scale of potential demand as the aviation sector moves toward lower-emission fuel alternatives.
The projection is linked to expectations for aviation fuel consumption and the gradual introduction of SAF blending requirements.
India has announced indicative SAF blending targets for international flights, including 1% from 2027 and 2% from 2028.
A further increase to 5% has been indicated for 2030.
These targets provide a policy direction for the development of the domestic SAF market.
However, actual demand will depend on implementation arrangements, the volume of aviation turbine fuel consumed and the availability of qualifying sustainable fuel.
The 3.8 lakh-tonne projection should therefore be treated as an estimate rather than a fixed statutory procurement obligation.
The scale of projected demand creates opportunities for biofuel producers, refiners, waste aggregators and technology providers.
At the same time, it places pressure on feedstock supply chains that are still developing.
Used Cooking Oil Emerges as a Strategic SAF Feedstock
Used cooking oil is an important potential raw material for sustainable aviation fuel production.
It is generated when edible oils are repeatedly used in food preparation.
Commercial establishments such as restaurants, hotels and food-processing facilities can produce recoverable quantities.
Rather than being discarded or improperly reused, suitable waste oil can be collected and processed into renewable fuels.
This creates a link between waste management and the energy transition.
However, used cooking oil must meet applicable quality and sustainability requirements before it can be used in certified fuel production.
Collection, storage and transport practices influence its suitability.
Contamination or poor handling can increase processing costs.
The availability of usable feedstock is therefore more important than estimates of total waste oil generation alone.
Why Used-Cooking-Oil Collection Is Difficult in India
India's food-service market includes a large number of establishments operating at different scales.
Major hotel chains and industrial food processors may generate relatively concentrated volumes of used cooking oil.
Smaller restaurants, roadside food outlets and independent kitchens may generate much smaller quantities.
Collecting oil from numerous small locations can be expensive.
Aggregators must coordinate collection schedules, maintain storage systems and transport material to processing facilities.
The economics become more challenging when individual suppliers generate limited quantities.
Informal collection practices can also complicate traceability.
A reliable SAF supply chain requires evidence that the material is genuinely waste oil and meets applicable sustainability criteria.
The combination of dispersed supply, logistics costs and documentation requirements creates a significant operational challenge.
India Formally Collects Only Around 6% of Used Cooking Oil
One of the most significant obstacles facing India's SAF industry is the low proportion of used cooking oil entering organised collection systems.
Industry estimates indicate that India generates approximately 18–26 lakh tonnes of used cooking oil annually.
However, only around 1.10–1.56 lakh tonnes are collected through formal channels.
This represents approximately 6% of estimated generation.
Estimated annual used-cooking-oil collection in India
6%
formally collected
The figures highlight the difference between theoretical feedstock availability and commercially accessible supply.
India may generate substantial quantities of waste cooking oil, but most of it is not currently captured by documented collection networks.
Expanding formal collection is therefore a critical requirement for SAF producers.
Even so, not every tonne of collected oil can be converted into one tonne of aviation fuel. Processing yields, feedstock quality and competing uses must also be considered.
SAF Demand Projections Differ Across Industry Assessments
The estimate of 3.8 lakh tonnes by 2030 is one projection of India's potential SAF requirement.
Other assessments indicate different demand levels.
For example, a September 2026 assessment by S&P Global Energy and the SAF Association estimated demand of approximately 2.5 lakh tonnes by 2030 under its stated assumptions.
These differences reflect variations in projected aviation fuel consumption, blending coverage and implementation scenarios.
|
Indicator |
Estimate |
|---|---|
|
SAF demand projection highlighted for 2028 |
65,000 tonnes |
|
SAF demand projection highlighted for 2030 |
3.8 lakh tonnes |
|
Alternative 2030 industry assessment |
Approximately 2.5 lakh tonnes |
|
Estimated annual UCO generation |
18–26 lakh tonnes |
|
Estimated formally collected UCO |
1.10–1.56 lakh tonnes |
|
Formal UCO collection rate |
Approximately 6% |
The figures should not be treated as directly interchangeable forecasts. The 3.8 lakh-tonne figure is a demand scenario, while the 2.5 lakh-tonne estimate reflects a different analytical framework.
Both indicate that India will need to expand feedstock availability and production capacity substantially.
HEFA Technology Provides an Established Production Pathway
The HEFA process is among the established pathways for producing sustainable aviation fuel from waste oils and fats.
The process involves treating eligible feedstocks with hydrogen and converting them into hydrocarbon fuels.
Further processing helps produce fuel components suitable for aviation applications.
However, SAF must meet applicable fuel specifications before it can be used in aircraft.
The final product is generally blended with conventional aviation turbine fuel within approved limits.
HEFA technology offers a pathway for converting used cooking oil into aviation fuel, but its economics depend heavily on feedstock availability and cost.
If waste oil prices increase because of competition among fuel producers, SAF manufacturing costs may also rise.
This makes secure feedstock procurement an important commercial consideration.
RUCO Initiative Provides a Foundation for Collection
India's Food Safety and Standards Authority of India (FSSAI) operates the Repurpose Used Cooking Oil initiative, known as RUCO.
The programme aims to divert used cooking oil away from the food chain and support its appropriate non-food use.
Repeatedly heated cooking oil can undergo chemical changes that make continued food use unsafe.
FSSAI has established a limit of 25% for total polar compounds in cooking oil.
Oil exceeding the applicable threshold should not be reused for food preparation.
RUCO supports the collection of used oil through authorised channels.
The programme has historically facilitated uses such as biodiesel and other non-food products.
A stronger collection ecosystem could also support sustainable aviation fuel production.
However, SAF manufacturers require additional attention to traceability, certification and feedstock suitability.
Industry Calls for Stronger Collection Enforcement
Industry participants have proposed stronger mechanisms to encourage food businesses to channel used cooking oil into authorised collection networks.
One proposal involves extended producer responsibility, or EPR.
Such frameworks can establish responsibilities for the collection or recovery of specified waste materials.
However, an effective collection system requires more than regulatory obligations.
Food businesses must have access to collectors capable of handling relatively small quantities.
Collection must also be economically viable.
Industry discussions at the India SAF Conclave in September 2026 emphasised the importance of strengthening first-mile collection networks.
Participants also highlighted the need for digital traceability.
Without adequate infrastructure, stricter disposal requirements may not translate into higher formal recovery.
Digital Traceability Could Improve Feedstock Reliability
Traceability is important for establishing the origin and movement of used cooking oil.
SAF producers may need documentation demonstrating that feedstock qualifies under applicable sustainability standards.
Digital systems can help record collection points, quantities, transfers and delivery to processing facilities.
Such information can support supply-chain verification.
It may also reduce opportunities for incorrectly identifying virgin oil or other materials as waste feedstock.
However, traceability systems must be practical for small businesses and collectors.
Excessive administrative costs could discourage participation.
The challenge is to establish reliable documentation without making collection commercially unviable.
Indian Oil's Panipat Project Demonstrates SAF Production Potential
Indian Oil Corporation has been developing sustainable aviation fuel production capabilities at its Panipat refinery in Haryana.
The project has been associated with planned annual production capacity of approximately 35,000 tonnes of SAF from used cooking oil.
The refinery obtained ISCC CORSIA certification for SAF production, marking an important step in establishing a certified domestic production pathway.
The project illustrates the role existing refinery infrastructure may play in India's early SAF development.
However, production capability does not eliminate the need for feedstock procurement.
Indian Oil has identified collection from hotels, restaurants and food businesses as an important requirement.
Large commercial establishments may offer relatively concentrated supplies.
Smaller outlets and households present greater logistical challenges.
Refinery Co-Processing Could Support Initial Targets
India may be able to use existing refinery infrastructure to support its initial SAF blending requirements.
Co-processing involves introducing suitable renewable feedstocks into certain conventional refining processes.
This approach can reduce the need for entirely new production facilities during early market development.
A September 2026 industry assessment suggested that existing domestic refinery co-processing capacity could support the initial 2027 blending target.
However, the higher 2030 target would require further investment.
Dedicated commercial-scale SAF facilities and stronger feedstock collection infrastructure may be necessary.
The availability of refining capacity should therefore be distinguished from the availability of raw materials.
Both must expand together to support sustained SAF production.
Other Indian Energy Companies Explore SAF Opportunities
Several Indian energy and engineering companies are involved in the development of SAF-related technologies, projects or infrastructure.
These include Indian Oil Corporation, Bharat Petroleum Corporation, Hindustan Petroleum Corporation and Mangalore Refinery and Petrochemicals.
Engineering and technology businesses such as Engineers India, Praj Industries and Larsen & Toubro may also participate in relevant project development and equipment supply.
However, involvement in the SAF ecosystem does not establish that every company has commissioned commercial SAF production capacity.
Projects may be at different stages of development.
They may also use different technologies and feedstocks.
Investors should distinguish between announced plans, certified production capability, commissioned facilities and actual fuel sales.
SAF Production Costs Remain Higher Than Conventional Jet Fuel
One of the main commercial obstacles to SAF adoption is its higher production cost.
SAF can cost substantially more than conventional aviation turbine fuel, depending on the feedstock, technology and market conditions.
Industry estimates have placed some SAF production costs at approximately three times those of conventional jet fuel.
However, this is not a universal price relationship.
Costs vary according to raw materials, energy inputs, plant scale and production pathways.
For airlines, fuel is a major operating expense.
Higher fuel prices can affect profitability and ticket pricing.
The transition to SAF therefore requires consideration of both environmental benefits and commercial affordability.
Long-term purchase agreements, production scale and policy support may influence market development.
Feedstock Competition Could Increase Costs
Used cooking oil is not exclusively used for sustainable aviation fuel.
It also serves as a feedstock for biodiesel and other industrial applications.
As SAF production expands, competition for eligible waste oils may intensify.
Higher demand could increase procurement prices.
This could weaken the economics of SAF manufacturing if producers cannot recover additional costs through fuel sales.
Competition may also create incentives for improved collection.
However, expanding collection takes time and requires investment.
The industry must therefore consider both feedstock availability and alternative uses when planning production capacity.
Agricultural Residues Offer an Alternative Feedstock Opportunity
India generates significant quantities of agricultural residues.
Some of these materials may be suitable for conversion into aviation fuels through appropriate technological pathways.
Using agricultural waste could diversify the SAF feedstock base.
It may also reduce dependence on used cooking oil.
However, agricultural residues present different collection and processing challenges.
They are often seasonal and geographically dispersed.
Moisture content, storage requirements and transportation costs can affect commercial feasibility.
Conversion technologies may also require substantial capital investment.
Agricultural residues therefore represent a potential long-term opportunity rather than an immediate substitute for all UCO-based production.
Municipal Waste and Other Pathways Could Support Diversification
Sustainable aviation fuel can be produced through several approved technological pathways.
Potential feedstocks include selected waste materials, agricultural residues and other eligible renewable resources.
Municipal solid waste may provide opportunities where suitable processing technologies and waste segregation systems are available.
Power-to-liquid fuels represent another pathway, combining suitable hydrogen production with captured carbon dioxide.
However, different pathways have different costs, energy requirements and environmental characteristics.
Not all renewable fuel pathways deliver the same lifecycle emissions reductions.
Certification and sustainability assessments are therefore important.
A diversified feedstock strategy could reduce dependence on any single raw material.
CORSIA Creates an International Aviation Framework
The Carbon Offsetting and Reduction Scheme for International Aviation, known as CORSIA, is an International Civil Aviation Organization framework addressing emissions from international aviation.
Its mandatory phase begins in 2027 for participating states subject to the applicable framework.
Eligible aviation fuels can contribute to emissions-reduction obligations when they meet the relevant criteria.
However, producing a fuel from biological material does not automatically make it CORSIA-eligible.
Sustainability certification and lifecycle emissions requirements are important.
India's SAF development plans are connected to the broader international aviation decarbonisation agenda.
The introduction of blending targets could create more predictable domestic demand.
Nevertheless, the final implementation framework and commercial conditions will influence actual market growth.
India's SAF Blending Roadmap Creates Demand Visibility
India's indicative blending roadmap focuses initially on international aviation.
The announced trajectory includes 1% SAF blending in 2027, 2% in 2028 and 5% by 2030.
These targets provide a basis for industry planning.
However, their practical effect depends on implementation, eligible fuel supply and the final regulatory arrangements.
Domestic aviation requirements may develop separately.
The government must also consider airline economics and fuel availability.
A clear implementation framework could support investment in production facilities.
However, investors and manufacturers will need confidence that sufficient feedstock can be procured at viable costs.
Aviation Growth Increases the Importance of Lower-Carbon Fuels
India's aviation market has expanded as passenger demand and airline networks have developed.
Growth in air travel increases demand for aviation fuel.
This creates a challenge for emissions reduction because commercial aircraft continue to rely heavily on liquid fuels.
Sustainable aviation fuel offers a pathway to reduce lifecycle emissions without requiring an immediate replacement of existing aircraft fleets.
However, the extent of emissions reduction depends on feedstock sourcing and production methods.
SAF does not eliminate emissions from aircraft engines.
Its environmental benefit is assessed across the fuel's lifecycle.
The industry must therefore consider both fuel volumes and verified sustainability performance.
Investment in Collection Infrastructure Will Be Essential
Scaling the SAF industry requires investment beyond fuel manufacturing plants.
Used-cooking-oil collection systems need storage containers, transport networks, aggregation facilities and quality-control procedures.
Collection companies must establish relationships with food businesses.
They also need reliable commercial arrangements with fuel producers.
Digital documentation and traceability may create additional infrastructure requirements.
Investment in these systems could increase the proportion of UCO entering formal channels.
However, collection economics will depend on the quantity recovered, transport distances and feedstock prices.
A commercially sustainable network must serve both large generators and smaller establishments.
Regional Collection Hubs Could Improve Economics
One possible approach involves developing regional collection hubs near areas with concentrated food-service activity.
Large cities contain restaurants, hotels and commercial kitchens that generate used cooking oil.
Aggregating supplies within defined geographic areas could reduce transport costs.
However, collection hubs must maintain appropriate handling and documentation standards.
The suitability of a location depends on waste generation, infrastructure and proximity to processing facilities.
Regional systems could also support smaller collectors by providing centralised aggregation points.
The development of such networks may improve supply reliability for SAF manufacturers.
Nevertheless, the commercial benefits would need to be demonstrated through actual operating performance.
SAF Market Growth Could Create Opportunities Across Industries
The development of a domestic SAF market could generate business opportunities in several sectors.
Refiners may invest in production facilities.
Engineering companies may provide equipment and project services.
Waste-management businesses could expand collection operations.
Technology providers may develop traceability and certification systems.
However, the timing and financial scale of these opportunities remain uncertain.
Project announcements do not necessarily translate into immediate earnings.
Investors must evaluate capital expenditure, feedstock availability, project commissioning and actual commercial sales.
The SAF industry is still developing in India, and near-term profitability may be limited by production costs and market scale.
What Investors and Industry Participants Will Monitor
Several developments will influence the next phase of India's SAF market.
The expansion of formal UCO collection will be particularly important.
Industry participants will also monitor the commissioning of production facilities and the availability of certified feedstocks.
Government decisions on blending implementation and incentives could affect investment.
Airline procurement commitments may provide additional demand visibility.
The commercial performance of early projects will help establish whether domestic production can scale competitively.
However, the 2030 demand projection alone does not establish guaranteed revenues for any particular company.
Outlook for India's Sustainable Aviation Fuel Industry
India has substantial potential to develop a domestic SAF industry.
The country's aviation market, refining infrastructure and waste-resource base provide opportunities for investment.
However, the low formal collection rate for used cooking oil represents a significant constraint.
Only approximately 6% of estimated UCO generation currently enters organised collection channels.
This limits the quantity of feedstock readily available to certified fuel producers.
Expanding collection systems could unlock additional supply.
Alternative feedstocks and production pathways may also support longer-term growth.
Nevertheless, the transition will require coordinated investment in waste collection, refining capacity, certification and fuel procurement.
The ability to address these challenges will determine whether India can meet its SAF demand projections by 2030.
Conclusion
India's sustainable aviation fuel industry faces a major feedstock supply-chain challenge as projected demand reaches as much as 3.8 lakh tonnes annually by 2030.
Used cooking oil offers an established pathway for producing lower-carbon aviation fuel through HEFA technology.
However, India formally collects only around 6% of the estimated 18–26 lakh tonnes of used cooking oil generated each year.
The remaining material largely sits outside organised collection systems, limiting its immediate availability for certified SAF production.
India's indicative blending roadmap of 1% in 2027, 2% in 2028 and 5% by 2030 creates a policy direction for market development.
Existing refinery infrastructure may support initial production requirements, but higher demand will require investment in dedicated facilities and feedstock networks.
The central challenge is therefore not simply building SAF plants.
India must also establish reliable collection, traceability and procurement systems capable of supplying those plants.
A diversified strategy involving used cooking oil, agricultural residues and other eligible feedstocks could strengthen long-term supply security.
The success of India's SAF transition will ultimately depend on converting theoretical waste-resource potential into certified, commercially viable aviation fuel.
 India Sustainable Aviation Fuel Demand May Reach 3.8 Lakh Tonnes by 2030 FAQs

POST A COMMENT (0)
All Comments (0)
Replies (0)